Market Overview and Industry Significance of the Counter-Drone Defense Systems Market
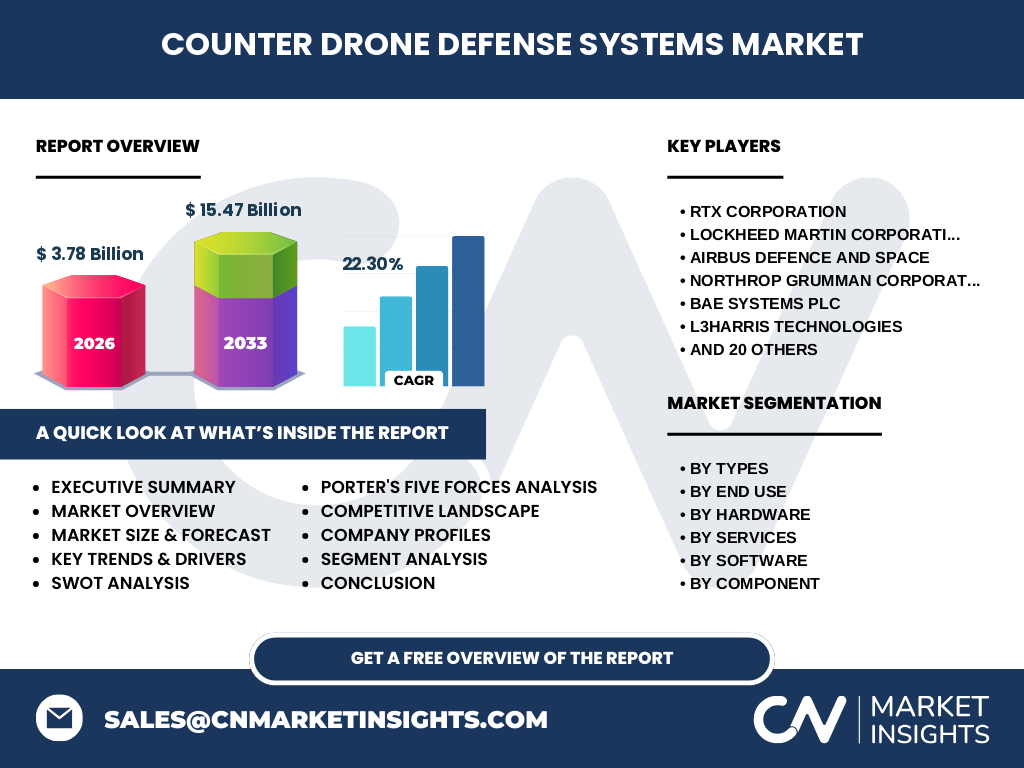
The Counter-Drone Defense Systems Market represents a critical sector valued at 3.78 Billion in 2026, driven by the escalating proliferation of asymmetric aerial threats. Our analysis indicates that this market encompasses advanced technologies designed to detect, track, identify, and neutralize unauthorized unmanned aerial vehicles across military and civilian domains, safeguarding vital infrastructure from modern aerial incursions.
Key Market Drivers, Restraints, Challenges, and Opportunities Shaping the Sector
Growth is heavily propelled by rising geopolitical tensions and asymmetric warfare tactics involving commercial drones. However, the market faces significant regulatory bottlenecks regarding airspace jurisdiction and spectrum interference constraints. Opportunities abound in developing high-power microwave systems and sophisticated artificial intelligence integration to counter swarming drone attacks effectively.
Emerging Trends and Growth Patterns in Counter-Drone Defense Systems
The shift toward multi-layered defense architectures defines current industry momentum. Integration of artificial intelligence into detection and tracking software allows operators to autonomously distinguish between biological clutter and actual threats, drastically reducing false alarm rates in dense urban airspace.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic initially caused severe supply chain disruptions for rare earth elements and semiconductor components essential for radar and radio frequency jamming hardware. Despite these logistical hurdles, the sector experienced a resilient rebound as governments prioritized border security and critical infrastructure protection.
Competitive Landscape and Strategic Dynamics
The market features intense competition among aerospace primes like RTX Corporation, Lockheed Martin Corporation, and specialized innovators such as DroneShield Limited and Epirus Inc. Industry leaders are pursuing aggressive mergers and acquisitions to combine kinetic interception systems with directed energy capabilities into cohesive product portfolios.
Executive Summary of the Counter-Drone Defense Systems Market
Our comprehensive research projects the global market to surge from 3.78 Billion in 2026 to 15.47 Billion by 2033, expanding at a robust 22.30% CAGR. Government and defense agencies remain the primary revenue generators, though commercial adoption in airports and energy facilities is accelerating rapidly.
Market Forecast from 2027 to 2033
Driven by persistent security threats and surging procurement budgets, the market is poised for explosive expansion. The projected trajectory from 2027 to 2033 will see valuations scale up to 15.47 Billion, fueled by investments in directed energy and autonomous command and control software.
Segmentation Analysis Across Hardware, Software, Services, and End Uses
The market segments by hardware, software, and services, alongside specific deployment vectors. Hardware includes radar systems, radio frequency jamming systems, electro-optical infrared sensors, acoustic detection sensors, command and control systems, interceptor drones, kinetic interception systems, and directed energy weapon systems. End uses span government and defense agencies, law enforcement agencies, airports and transportation authorities, industrial and energy facilities, and event management organizations.
Regional Market Analysis and Geographic Performance
Geographic performance is led by North America, supported by robust defense spending from the Department of Defense. Meanwhile, the Asia-Pacific region demonstrates the fastest regional adoption rate, driven by territorial disputes and modernization initiatives across national military apparatuses.
In-Depth Regional Review of High-Growth Zones
Europe presents a specialized landscape governed by stringent European Union aviation safety regulations and localized cross-border security concerns. Urban centers in the Middle East drive demand for fixed and mobile drone defense equipment to protect critical oil and gas energy facilities.
Company Profiles and Strategic Positioning
Industry giants like Northrop Grumman Corporation and Thales Group leverage deep systems integration expertise, while agile firms like Anduril Industries Inc. and Fortem Technologies Inc. dominate through software-defined architecture and proprietary AI identification algorithms tailored for rapid tactical deployment.
Porter's Five Forces Analysis of the Industry
Supplier power remains moderate due to specialized electronic component dependencies, whereas buyer power is high among sovereign defense agencies. Threat of new entrants is mitigated by high research and development barriers, though technology startups frequently disrupt the space through software innovations.
SWOT Analysis of the Counter-Drone Defense Systems Market
Key strengths lie in advanced sensor fusion and directed energy capabilities. Weaknesses include high acquisition costs. Opportunities exist in civilian airspace management integration, while severe threats stem from the rapid technological evolution of consumer drone firmware evading traditional RF jammers.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with raw material suppliers providing gallium arsenide and semiconductors, progressing to hardware manufacturers and software developers. System integrators assemble these components before deployment by end-users across military and civilian sectors via installation and maintenance services.
Investment Insights and High-Potential Areas
Investors should focus on artificial intelligence based identification software and directed energy weapon systems. These areas offer superior margins and address the critical operational requirement of scaling neutralization capabilities against mass drone swarms cost-effectively.
Conclusion and Key Takeaways for Stakeholders
The Counter-Drone Defense Systems Market offers exceptional growth potential, anchored by a projected 22.30% CAGR through 2033. Stakeholders must prioritize software adaptability and multi-sensor fusion to capture market share in both defense and commercial domains.
Research Methodology and Baseline Estimation
Our baseline estimates are rigorously triangulated by combining global trade registry data, primary stakeholder interviews with defense contractors and military officials, and secondary macroeconomic indicators to ensure high fidelity and reliable market sizing.
Scope of the Report and Coverage Parameters
This report covers global market dynamics for counter-drone technologies across fixed and mobile configurations, hardware, software, and services. Limitations include restricted access to classified military black-budget expenditures and localized export control restrictions governing dual-use RF jamming hardware.
Recent Developments, Partnerships, and Strategic Moves
Recent market activity highlights extensive cross-industry collaboration. Companies like Elbit Systems Ltd. and Rafael Advanced Defense Systems Ltd. have secured major defense contracts, while startups focus on strategic product launches emphasizing low-collateral-damage interception solutions for densely populated civilian areas.